
Yes — you can run a credit check without a Social Security Number. The bureau matches the consumer’s file using other identifiers: an ITIN where the applicant has one, plus full name, date of birth, and current and prior addresses. Match confidence is lower than an SSN-based pull, so the result needs verification before you act on it.
For lenders, nothing else changes. FCRA permissible purpose, fair-lending rules under ECOA, and adverse-action notice obligations all apply in full.
Do You Need an SSN to Run a Credit Check?
No. The Social Security Number is the strongest single identifier in credit reporting, but it isn't required to request a report — and it isn't always available. Lenders regularly encounter applicants who can't or won't supply an SSN: holders of an Individual Taxpayer Identification Number (ITIN), recent immigrants, some international students and workers, and consumers who decline to share an SSN over identity-theft concerns. In each case the question is the same: can you still pull usable credit data, and can you do it compliantly?
The short answer is usually yes — but it changes how you collect identifiers, how you verify the result, and how carefully you document the file. This guide covers the practical workflow, the accuracy tradeoffs, and the compliance obligations that don't go away just because the SSN does.
How Bureau Matching Works Without an SSN
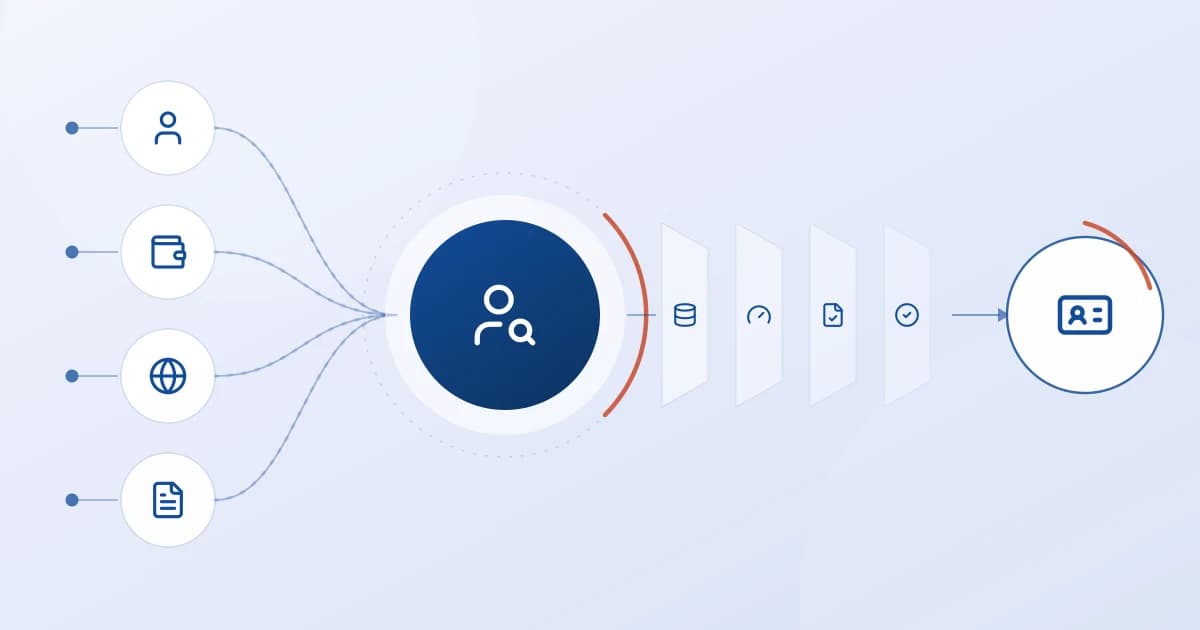
It's worth being precise about where the matching actually happens. When you request a report without an SSN, the credit bureau — Experian, Equifax, or TransUnion — attempts to locate the consumer's file using the other identifiers you supply. The bureau runs the match; the lender supplies clean inputs and evaluates the result. No lending platform "matches" credit files itself.
The identifiers that drive a non-SSN match, roughly in order of how much they narrow the result:
- Full legal name, including middle name or initial
- Complete date of birth
- Current address with full ZIP (ZIP+4 where available)
- Previous addresses — two or three recent ones materially improve matching
- ITIN, where the applicant has one
- Driver's license or state ID number
The more of these you provide, and the more accurate they are, the higher the match confidence the bureau can return.
The Accuracy Tradeoff — and Why Verification Matters More
A non-SSN match carries more risk of returning the wrong file or no file at all. Common names, shared household addresses, similar birth dates among family members, and name variations (nicknames, maiden and married names) all raise the chance of a false or ambiguous match.
That makes post-pull verification a compliance issue, not just an operational one. Under the Fair Credit Reporting Act, you're responsible for using reports accurately; acting on a mismatched file can mean making a decision about the wrong person. Practical safeguards:
- Cross-check the returned address history against what the applicant provided
- Confirm the date of birth and any name variations line up
- Sanity-check that the account history is age-consistent
- When the match is ambiguous, treat it as incomplete and request more identifiers rather than proceeding on a guess
The Compliance Obligations That Don't Change
Removing the SSN from the equation changes the mechanics of the pull. It changes none of the legal obligations around it.
Permissible purpose still comes first. The FCRA requires a permissible purpose before a report is requested. A genuine, consumer-initiated application for credit generally establishes one. Pulling reports for lead qualification, marketing, or "preliminary assessment" of someone who hasn't applied is a different matter and is not automatically permissible — this is exactly where well-meaning lenders create exposure. If your use case isn't a clear application for credit, confirm it with counsel before pulling.
Fair-lending rules apply equally. Many non-SSN applicants are ITIN holders or recent immigrants. National origin is a prohibited basis under ECOA and Regulation B. You may legitimately need extra identifiers to match an ITIN applicant's file — but the credit decision must rest on the same standards you'd apply to anyone else. Needing more data to find the file is not a reason to apply different terms.
Adverse action obligations are unchanged. If you decline an application — including because you couldn't obtain a reliable credit file — ECOA's notification rules still apply: notice within 30 days of a completed application, including the specific reasons or the applicant's right to request them within 60 days. A "no match found" outcome does not exempt you from providing proper notice.
Can a Company Report to a Credit Bureau Without an SSN?
Furnishing data is a different question from pulling it, and the answer is more cautious. A furnisher can report an account without an SSN, but the Social Security Number is what bureaus lean on most heavily to attach a tradeline to the right consumer file. Without it, the bureau falls back on name, date of birth, and address — the same weaker signals that make a non-SSN pull less certain.
The risk profile inverts, though. On a pull, a weak match usually means no file or an obviously wrong one, and you can catch it. On a furnish, a weak match can silently attach the account to someone else's credit report, and the person who finds out is the consumer whose file it landed on.
FCRA Section 623 makes the furnisher responsible for the accuracy of what it reports, so the practical guidance is straightforward: report every identifier you hold rather than the minimum, include an ITIN where the consumer has one, and make sure your dispute-investigation process can actually unwind a mis-attached tradeline when someone challenges it.
Where LASER Credit Access Fits
LASER Credit Access is the Salesforce-native ACCESS layer between your lending team and the bureaus. For non-SSN applicants, that means the alternative identifiers — name, DOB, address history, ITIN — are captured in the same Salesforce records your team already works in, passed to Experian, Equifax, TransUnion, or to Plaid for bank and income verification, and the structured results returned directly into the workflow. As a Plaid reseller and a pre-built, pre-configured Salesforce integration, LASER handles the plumbing and the audit trail; the bureaus handle the matching. The same workflow covers standard applications too — here's how to access credit reports in Salesforce in an FCRA-compliant way.
The compliance value is in the workflow, not in any proprietary scoring. Permissible-purpose capture, consistent identifier collection, and a documented record of what was requested and returned all live inside Salesforce — which is precisely what you want to be able to show when accuracy or fair-lending questions arise.
The Bottom Line
Accessing credit data without an SSN is feasible and, for a growing share of applicants, necessary. The discipline it requires is straightforward: collect more identifiers, verify the match before you rely on it, and remember that permissible purpose, fair-lending, and adverse-action obligations apply in full. Handled inside a system that captures the workflow and the documentation, serving SSN-free applicants becomes a routine, auditable part of lending — not a compliance gamble.
This article is for informational purposes and does not constitute legal advice. Consult qualified legal counsel for guidance on your institution's specific FCRA and ECOA obligations.
Related reading: For the broader workflow this fits into, see our guide on improving the loan approval process.